Redesigning a two week lending decision to under 15 minutes
Redesigning experiences for NAB Business Customers
- Leadership and people
- Service design
- Product Design
- Research
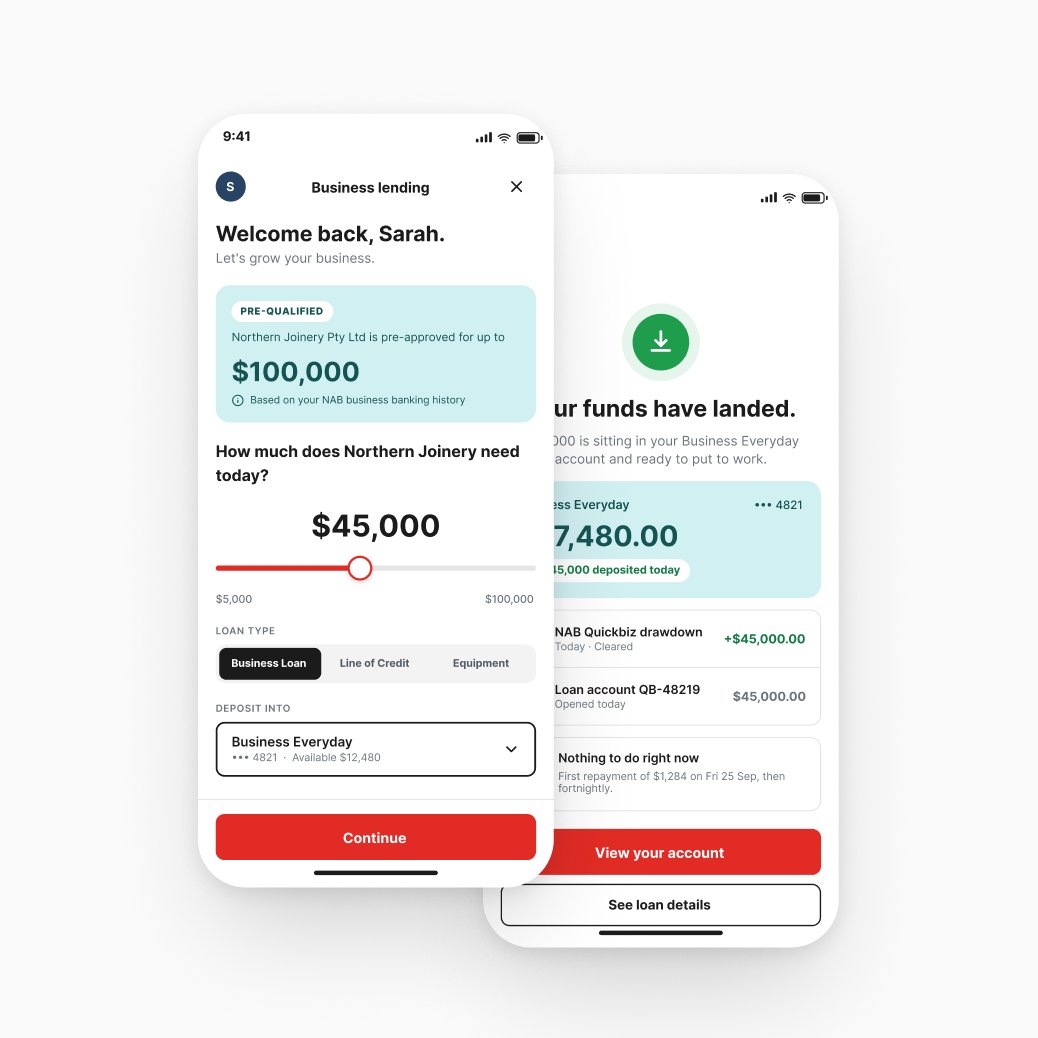
My role - Design Lead, Business Lending Customer Journey
I was Design Lead for the full Business Lending customer journey program and Quickbiz was a stream, providing unsecured lending for existing customers. I led the work from service design right through to product design delivery. I secured the funding, executive backing and access needed to expand the team, and to test with real customers and real bankers each sprint. At peak, the Quickbiz stream had a team of 4 product designers, 1 service designer, and 1 accessibility specialist.
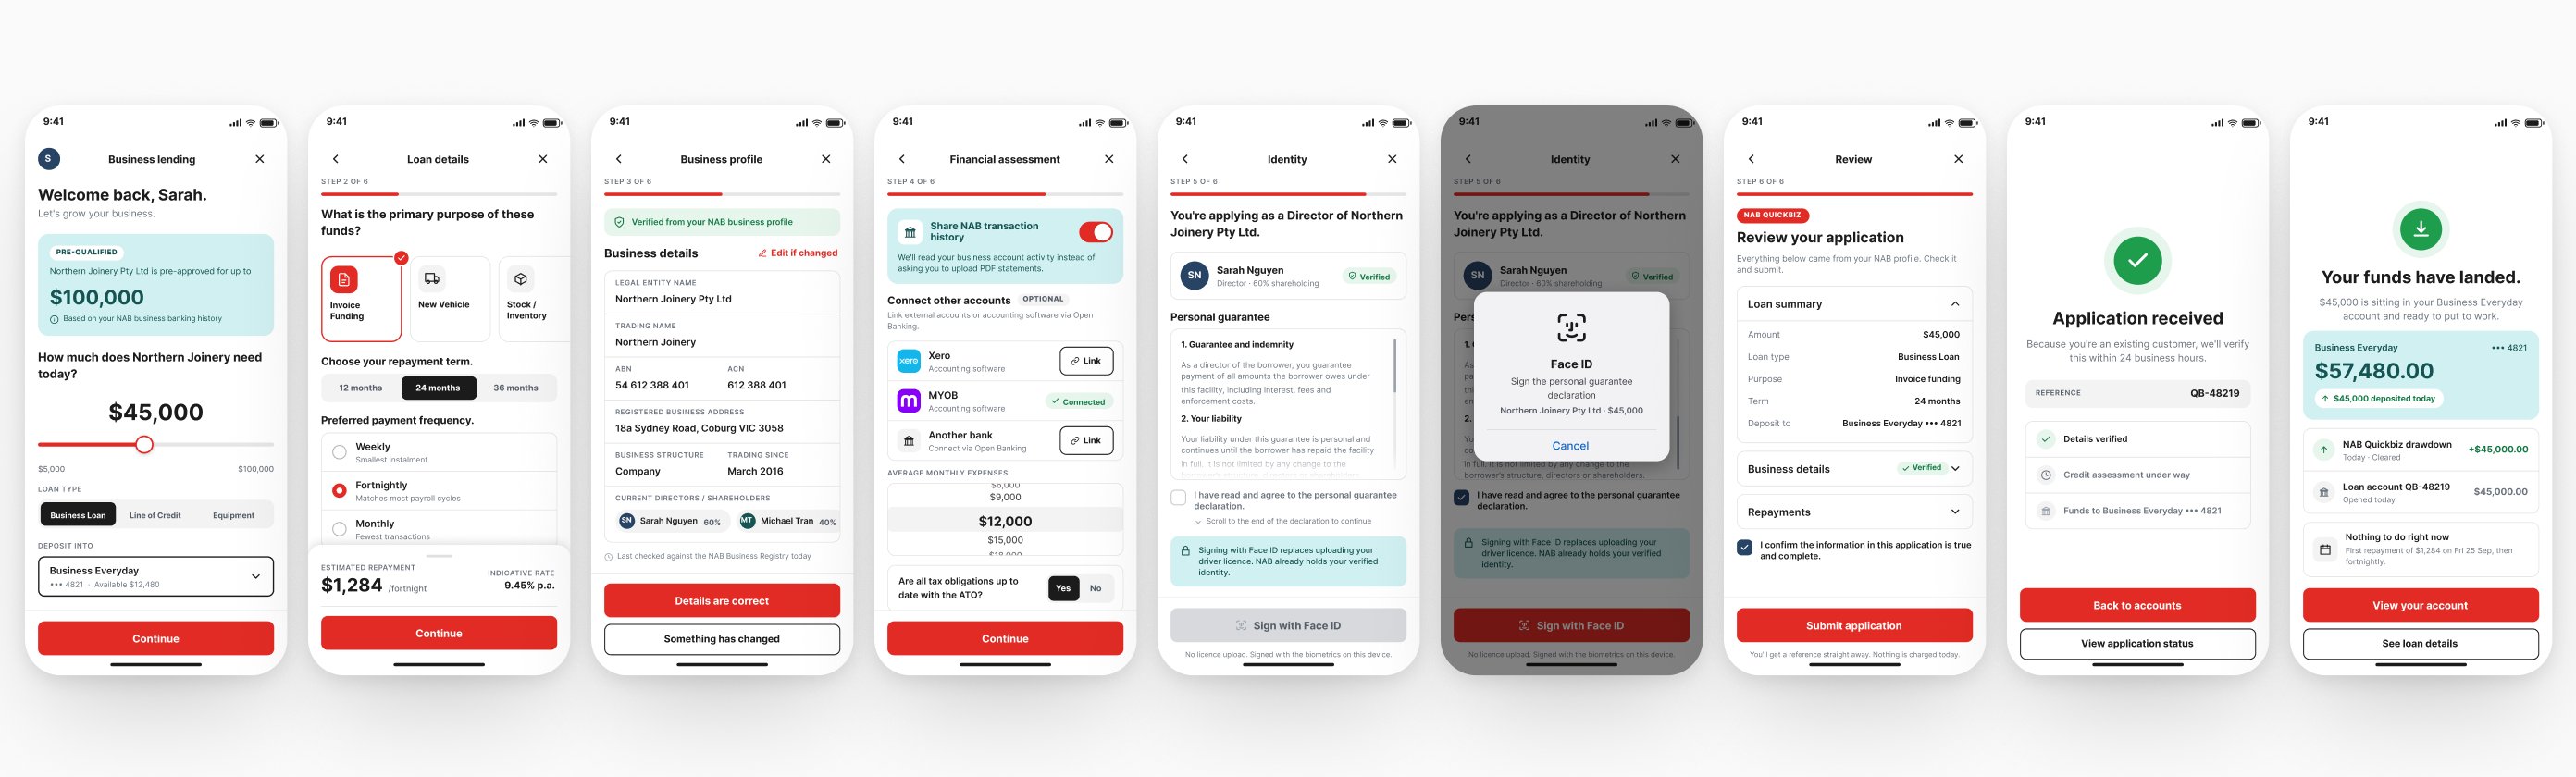
My leadership - key results
Application time
2 weeks, now 15 mins
Removal of a key pain point for customers by getting them an answer in minutes
Process simplified
15+ hand-offs removed
Reduction in hand-offs meant less friction, less opportunities for mistakes and much less frustration for bankers and customers
Human centred
189 users tested with
Keeping the customer and banker at the centre of the Business Lending journey
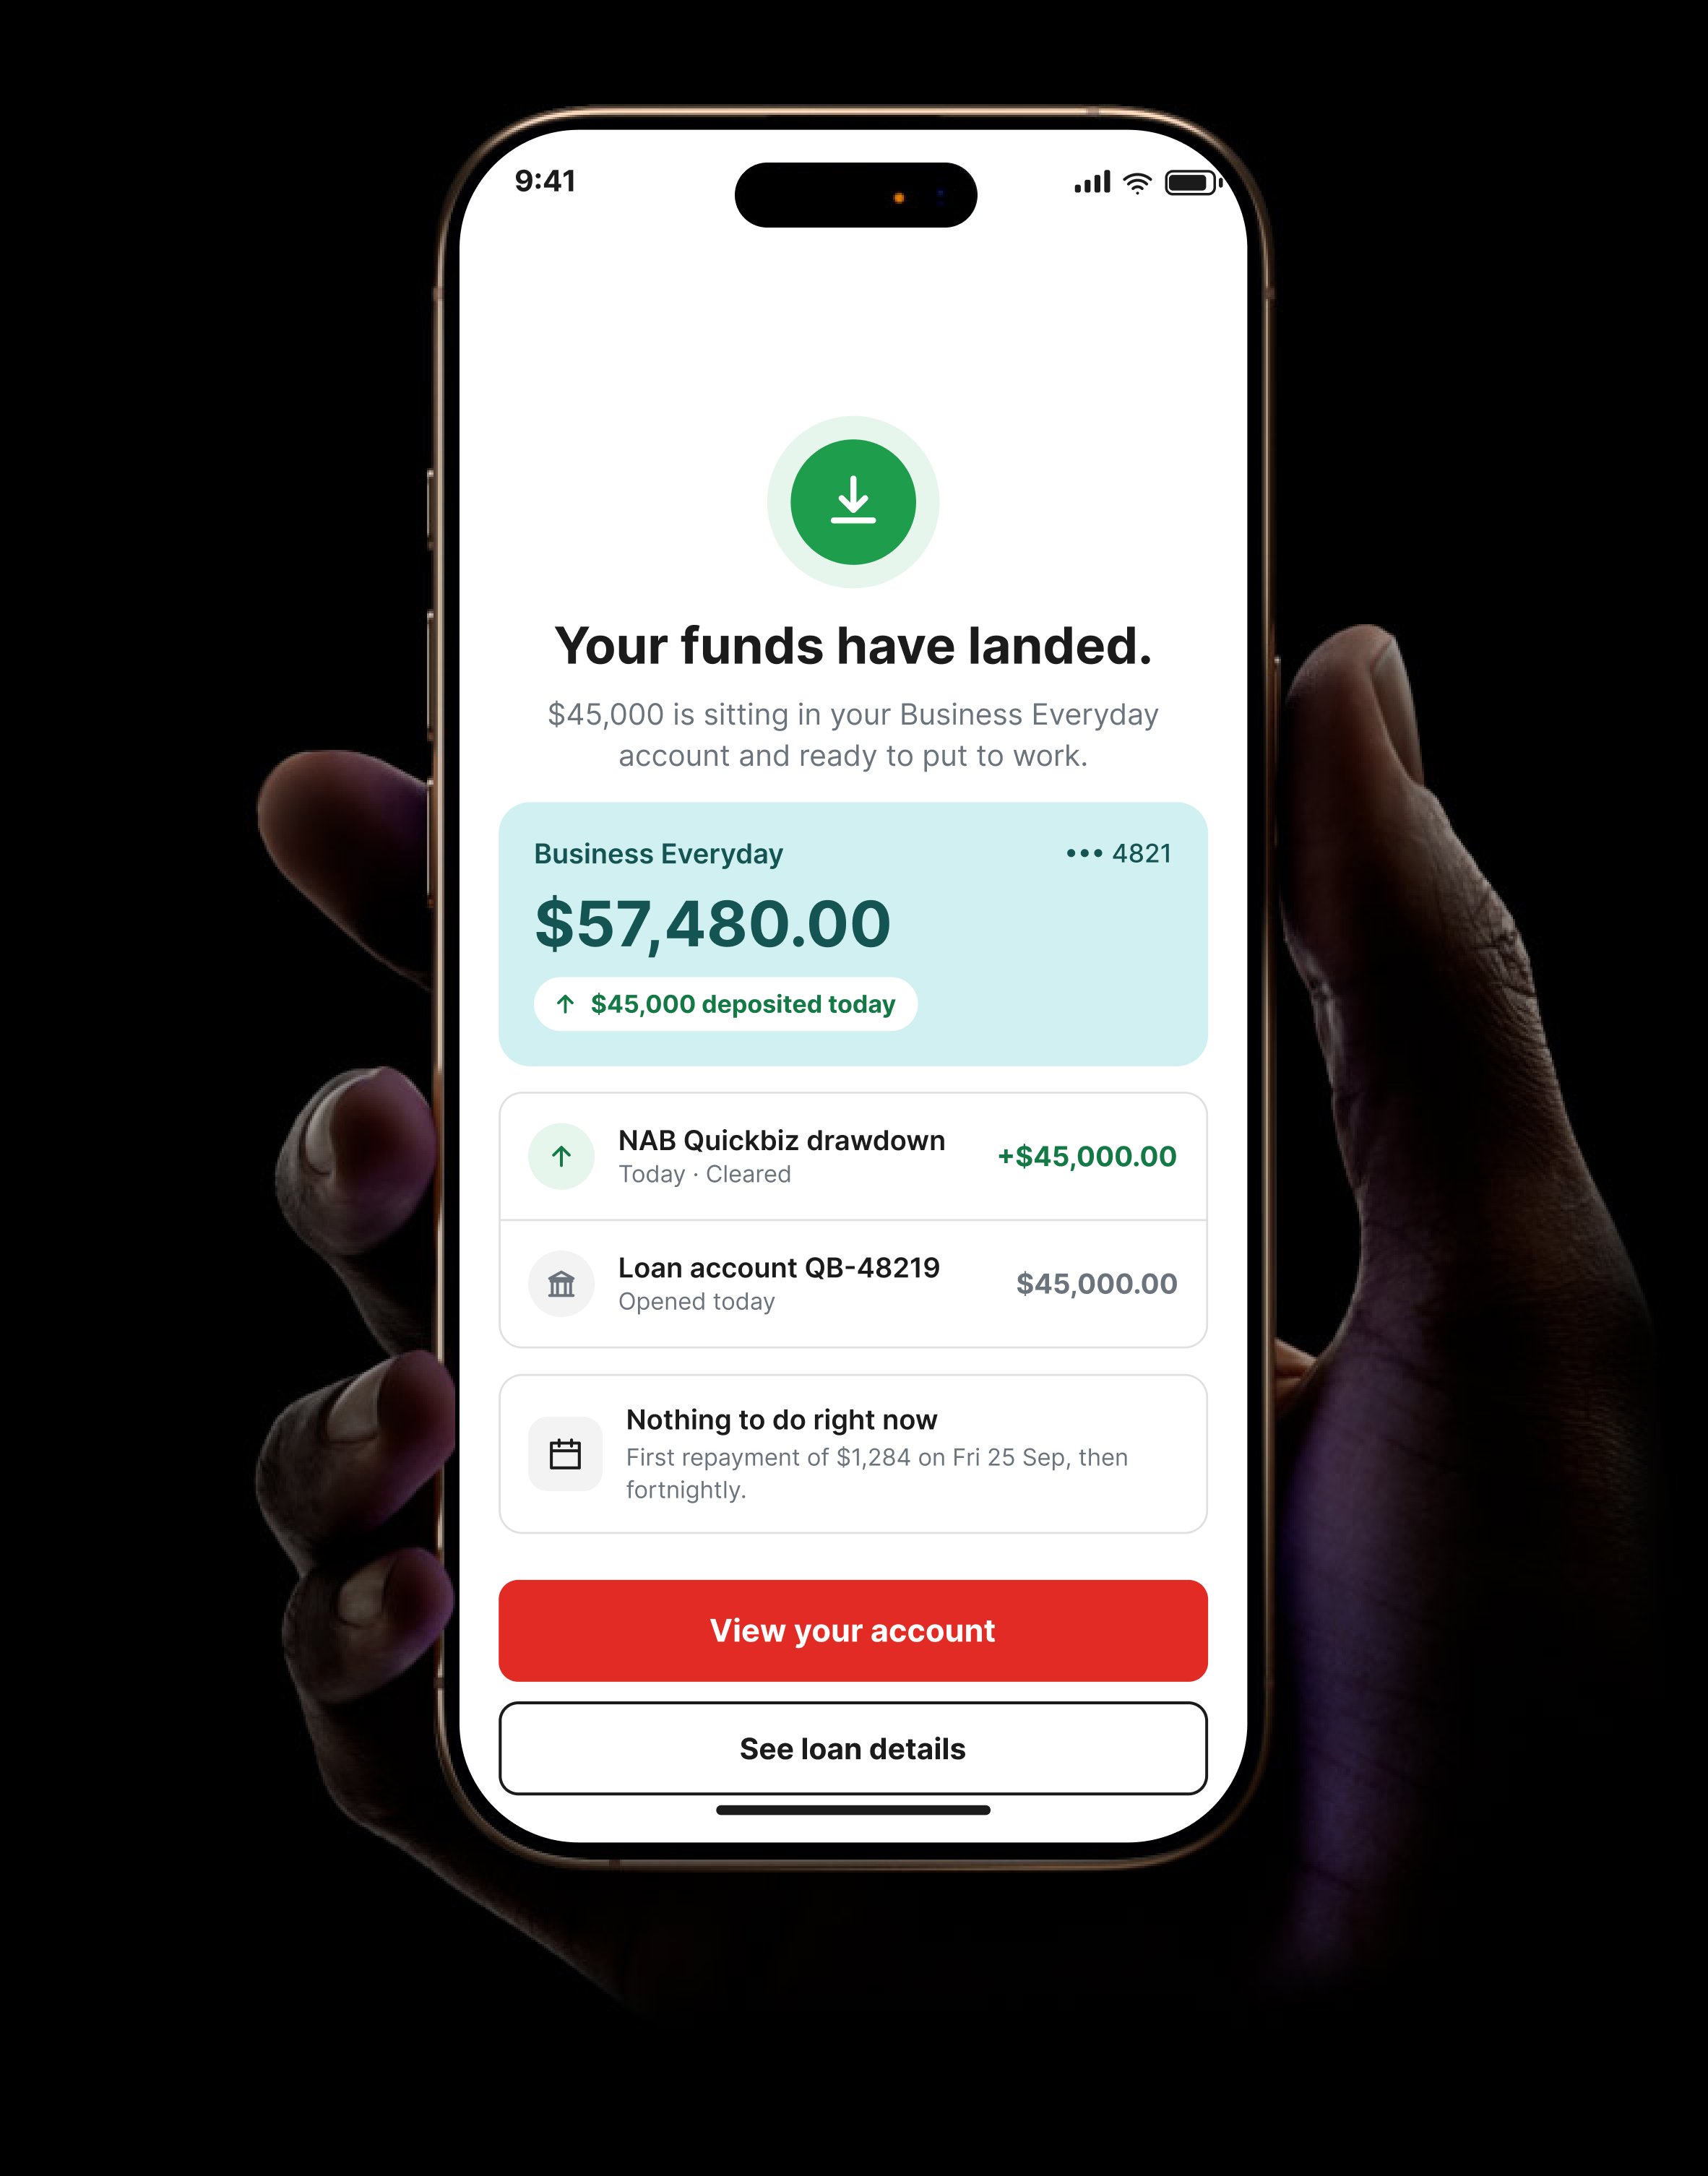
My approach - the key steps to success
-
01
Created a Service blueprint
Design leadershipThe service designer and I built the end to end blueprint across customer, banker, credit, and back office. We then presented this to the Business Lending Executive as a count of manual steps we could remove and this was the clincher that got us additional funding.
-
02
Tested with customers and bankers every sprint
ResearchUsing Optimal Workshop, we tested seven customers and seven bankers a round, in dedicated sessions, including engineers and product owners along the way. I led the work and set the rhythm up myself, then handed it to the team to continue.
-
03
Partnered with Engineering early
RelationshipsWhat we designed had to be something we could integrate with existing systems, so engineering constraints shaped the work as it was made, rather than trimming it back afterwards.
-
04
Built the funding case for more design resources
Stakeholder influenceUsing my relationship with the executive, I was able to pitch the need and cost case for a fourth product designer and a dedicated accessibility specialist. Accessibility assessment at the service layer prevented rework in delivery.
-
05
Kept scope in check
Strategic planningDigital signatures is a big process for a heavily regulated bank. I ensured that we demonstrated how big and how important Digital signatures was, and successfully made the case for it to be its own project with its own funding.
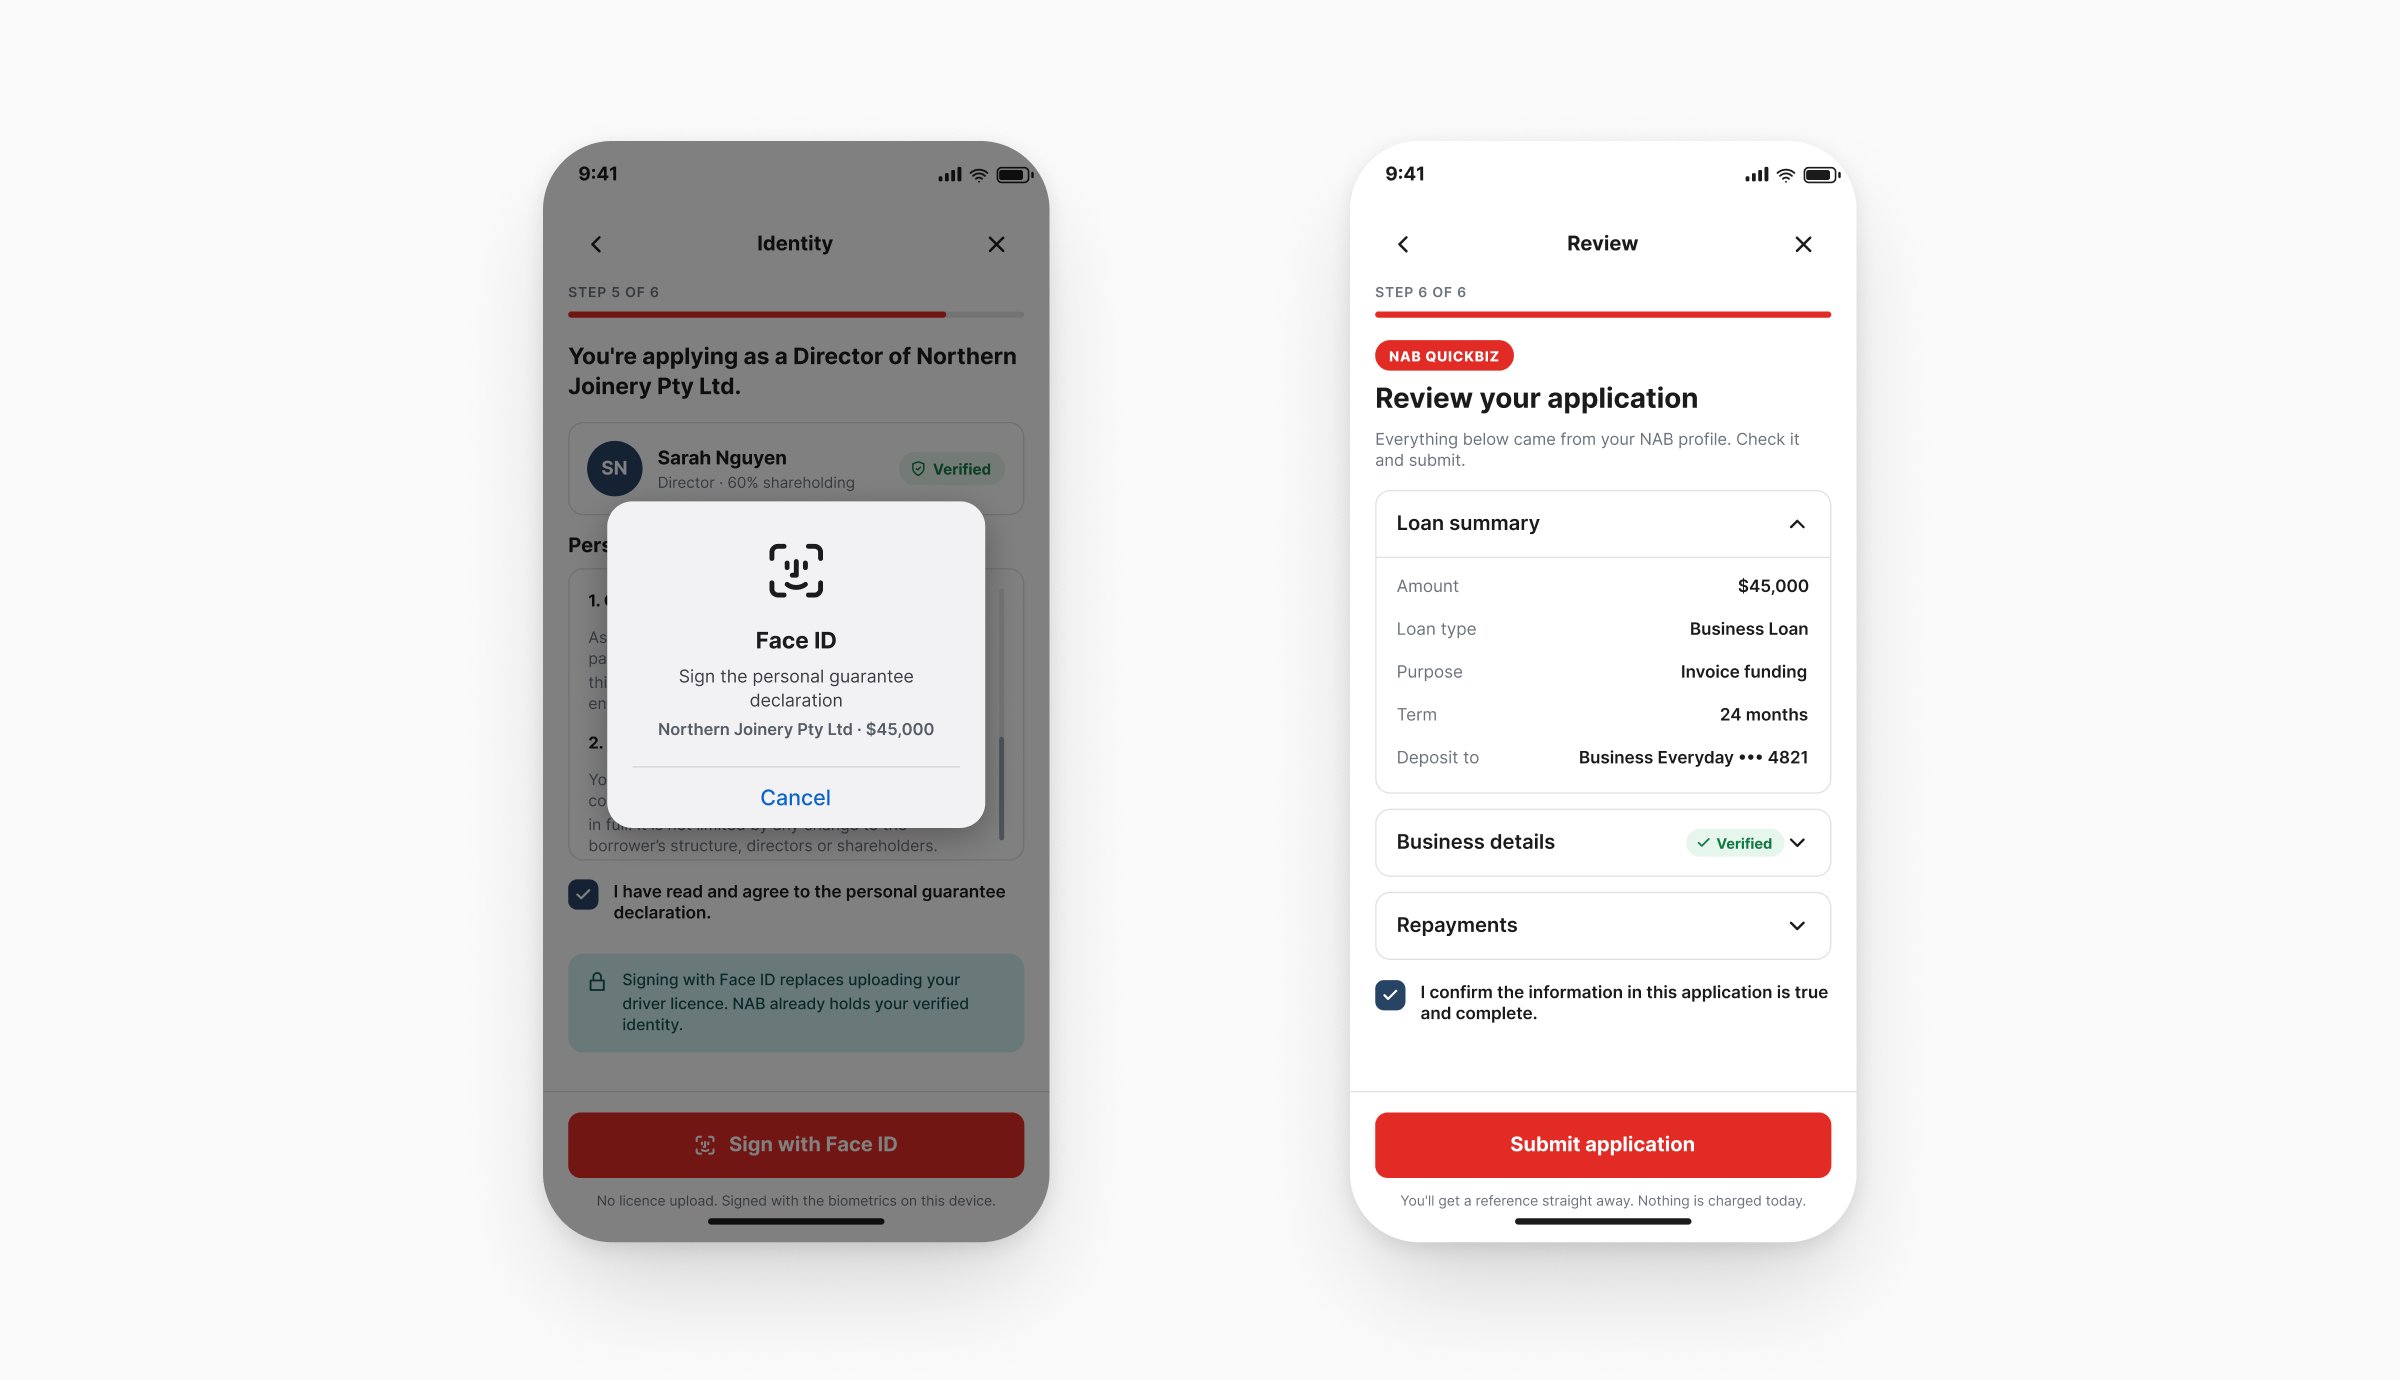
The impact
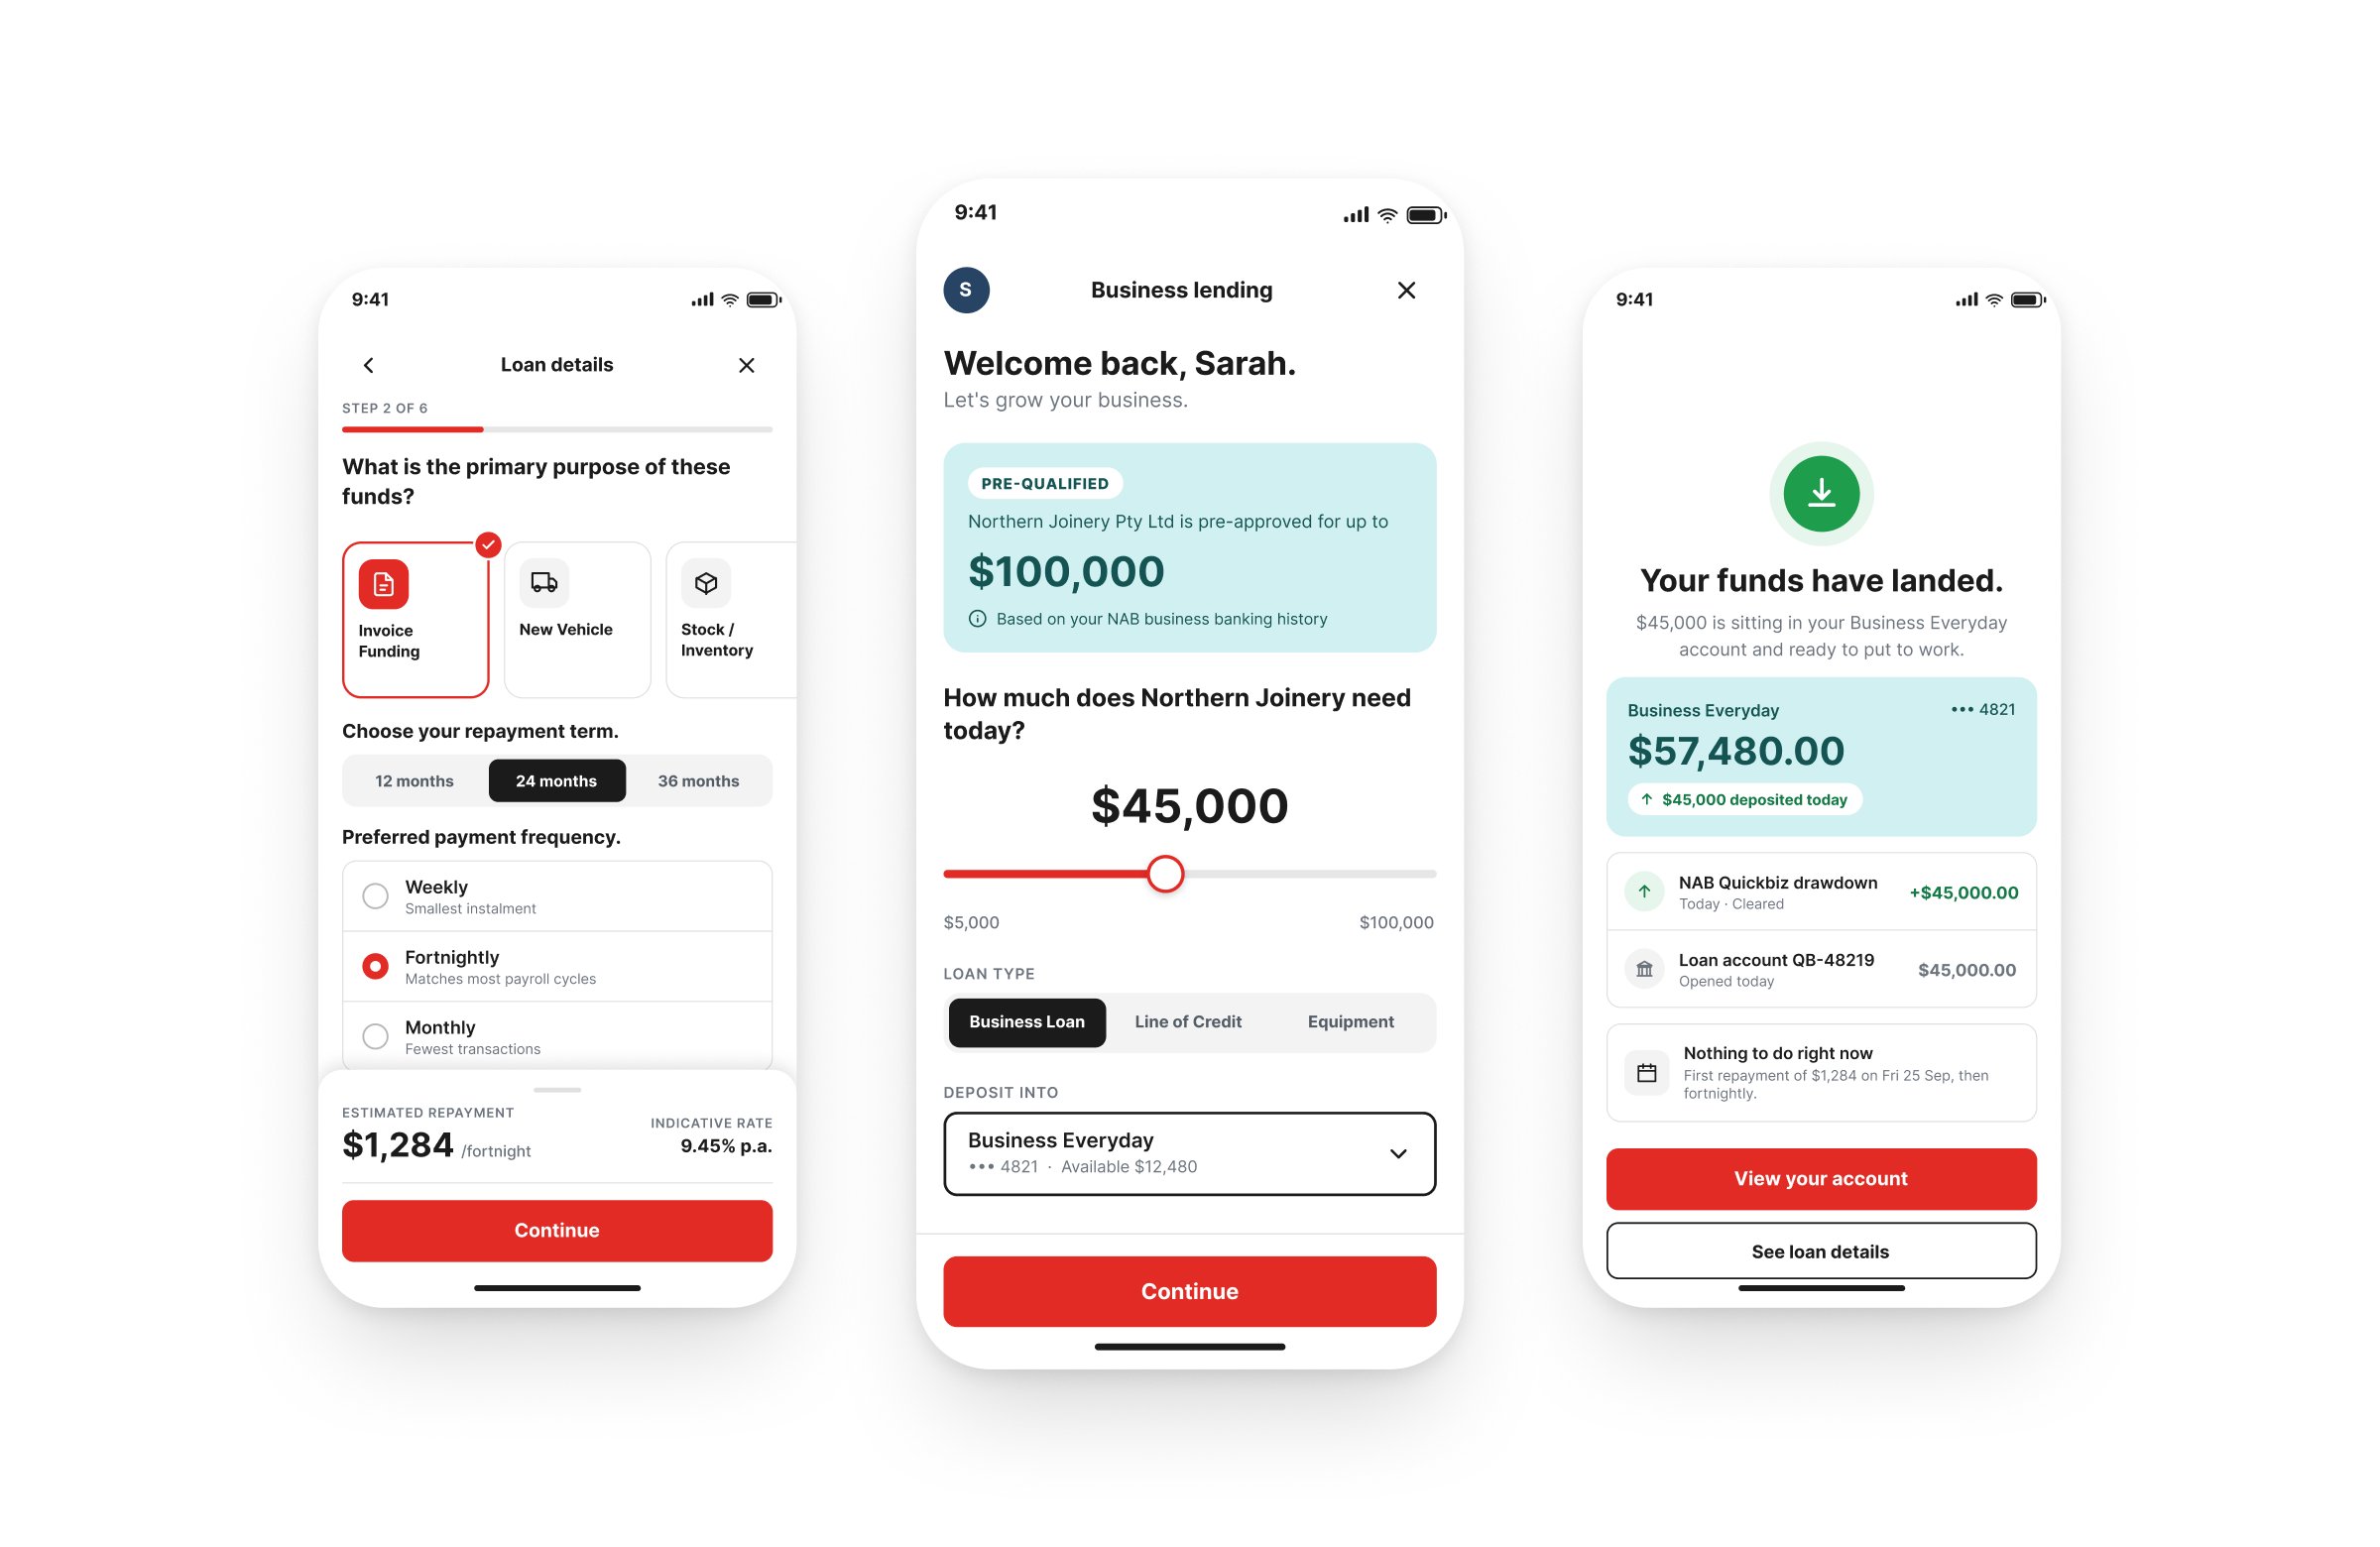
My Design Leadership meant that NAB Business customers who were previously waiting up to 2 weeks for an answer, can now self-serve within 15 minutes. This is a piece of work I am incredibly proud of.
What I would do differently
The similarities between Business lending and Home lending are numerous and in hindsight, I would’ve aligned better with the Home lending team to share patterns and research findings. Once both streams had delivered fantastic experiences, we all realised that we’d gone down similar paths. An example is the huge investment in customer testing - we could’ve shared this expense across business units and also shared the findings.
Luckily, we learnt from this and Business and Home lending shared resources and effort for the Digital signatures piece of work.